
The card that asks you nothing and tells you little
 Available in US
Card2Crypto sells a prepaid virtual Mastercard that you buy with crypto, with no identity check at any point. That is the whole appeal, and it is real: the card’s own pages say cards can be purchased and activated without KYC, from anyone worldwide. It is also the whole problem, in miniature. The pages I could read leave the issuer unnamed, the registration country unnamed, the conversion fee unstated, the ATM situation unstated, and the refund position only partially described. So this is not a review of a card that hides a bad deal behind good marketing — it is a review of a card that publishes very little at all, and I think you should read it that way before you read anything else about it.
The conditions described here are current as of October 28, 2026.
My score for the card is 6.0 out of 10. That is not a rounding of “no opinion”: it is a card that does one thing well and is unusually quiet about most of the others. Whether that silence is a problem depends entirely on what you need the card for.
The score, criterion by criterion
| Criterion | Mark | Why |
|---|---|---|
| Who can get it | 8 / 10 | “Anyone worldwide can purchase”, but activation can be refused to residents of a list of 30 countries, Russia, Belarus, Serbia, Turkey and Ukraine among them |
| Cost | 5 / 10 | “no fee stated” on the page; card value runs from 5 USD to 499 USD; the 4–7% fee on the page belongs to the PayPal gift card, not to the Mastercard |
| Top-up options | 8 / 10 | USDT (Polygon), USDC (Polygon), Bitcoin, Ethereum, Solana, Monero; repeat top-ups are not mentioned |
| Reliability and complaints | 4 / 10 | Card2Crypto is software services only per the terms; issuer, country of registration and licences are unnamed; no 3D Secure; no reviews found |
| Everyday use | 5 / 10 | Virtual Mastercard only, “Supports Apple Pay & Google Pay”; no plastic, ATM position not disclosed |
Total: 6.0 / 10.
The shape of that table is the review in miniature. Access and funding are where the card is strong: wide eligibility, a decent spread of coins, no paperwork. Reliability is where it is weakest, and not because something bad happened — because nothing is documented. Emitter, licences, complaints: all blank.
Who the card is for, and who it will turn away
Start with the good news, because it is genuine: the card’s pages say anyone worldwide can purchase. There is no nationality test, no residency paperwork, no income requirement, no branch, no interview. For someone who has been refused an ordinary bank card, that is not a small thing.
Then the list you need to read twice. Activation may be denied to residents of Afghanistan, Albania, Belarus, Bosnia & Herzegovina, Burma/Myanmar, Central African Republic, Croatia, DR Congo, Cuba, Ethiopia, Iran, Iraq, North Korea, Lebanon, Libya, Mali, Nicaragua, Palestine, Russia, Saudi Arabia, Serbia, Somalia, South Sudan, Sudan, Syria, Turkey, Ukraine, Venezuela, Yemen and Zimbabwe. That is residence-based, not citizenship-based — worth keeping straight, because the two are treated differently in this industry generally, and because a long holiday or a work posting can put you inside the list without a permanent address there.
One more line on that page deserves quoting in full, because it is the kind of sentence people skim. Attempting to redeem or activate a card from a Restricted Country “will void any right to a refund”. So the check happens at activation, not at purchase. You can apparently pay first and be refused afterwards.
So who does this card actually suit? Someone paying a supplier, a subscription or an online invoice who needs a card number now and has no route to a bank card. Someone whose crypto already sits on-chain in a wallet and who does not want it moved through an exchange with its own paperwork. Someone who values not being asked for a passport over everything else.
Who it does not suit: anyone planning a holiday on it. A single-country list of 30 refusals is a small sample of how merchant-side checks work, and the card’s own funding side is US dollars only. Anyone who wants to raise a dispute when a payment goes wrong — there is no 3D Secure, and the terms point disputes at the courts of a home country that is never named. And anyone who intends to hold a balance on the card for long, which is covered further down.
Getting the card: no KYC, a ten-minute timer, minutes not weeks
There is no application form in the traditional sense, and there are no KYC levels — none, at any tier. The card’s pages put it plainly: all cards can be purchased and activated without KYC.
What activation may still ask for is worth planning around, because “no KYC” and “no information” are not the same claim. Activation may need a valid name, email address, phone number and billing address. That is not a document check, and it is not an identity verification; it is contact and address detail. If you have never given those anywhere before, this is where you will meet the requirement for the first time.
The sequence itself is short. You choose an amount, you pay in crypto, and there is a 10:00 timer on the payment. The card is typically ready within minutes. Under heavy demand that stretches to up to 48 hours.
The card you receive is a prepaid virtual debit Mastercard, and the balance is in USD. There is no plastic version — virtual only. Cards do not support 3D Secure, which I will come back to, because it is the single detail most likely to cause you a declined payment and the single detail most readers will not have noticed until the decline.
What it really costs
Here is the honest version: the card’s public page says “no fee stated”. Not zero — not stated. The value you load is between 5 USD and 499 USD. No monthly fee is stated. There is one card product; the PayPal and Binance gift cards on the same page are separate products.
| Fee or limit | What the card states |
|---|---|
| Issuance fee | Not stated; card value runs from 5 USD to 499 USD |
| Monthly fee | Not stated |
| Conversion / FX fee | Not stated for the Mastercard; the 4–7% shown on the page applies to the PayPal gift card |
| ATM / cash withdrawal | Not stated |
| Daily limit | Not stated |
| Monthly limit | Not stated |
| Spend limits | Not stated |
| Balance currency | USD; multi-currency not stated |
Two rows deserve emphasis because they are easy to misread. The 4–7% fee is real, it is on the same page, and it is not your fee — it belongs to the PayPal gift card product. And the absence of a stated conversion fee is not evidence of one. It means nobody has told you.
Let me take three ordinary payments and be explicit about which fees apply, because that is the only way to make an undisclosed-fee table usable.
A software subscription billed in USD. If the merchant charges USD, you are spending the USD already sitting on the card. No conversion is involved, so whatever conversion or FX fee exists is not triggered by this purchase. What you paid to load the balance still stands — you bought crypto to reach it — and any on-chain network fee for that transfer was charged by the blockchain, not by the card.
A subscription in euros, paid from the same card. This is where the unknown lives. The card holds a USD balance, so spending euros requires conversion at a moment when the rate is not published on the page, and the cost of that conversion is not stated. Budget for it as a real and unquantified cost, because it is one. You cannot compute your effective price per euro from what is written.
A cash withdrawal. Whether the card permits it at all is not stated, and the fee is not stated. Two unknowns where there is usually at least one. If cash is part of what you need this card for, that is a question to put to the support contact before you load anything.
The general rule about crypto card costs is worth holding on to: on-chain network fees for your deposit are charged by the blockchain, not by the card provider. That part is fixed and knowable. Everything between your wallet and the merchant’s till is where this card is quiet.
Top up
Funding is the strongest part of the offer and the clearest thing the pages tell you. You can pay with USDT, USDC, BTC, ETH, SOL or XMR. The dropdown is more specific: USDT on Polygon, USDC on Polygon, Bitcoin, Ethereum, Solana, Monero.
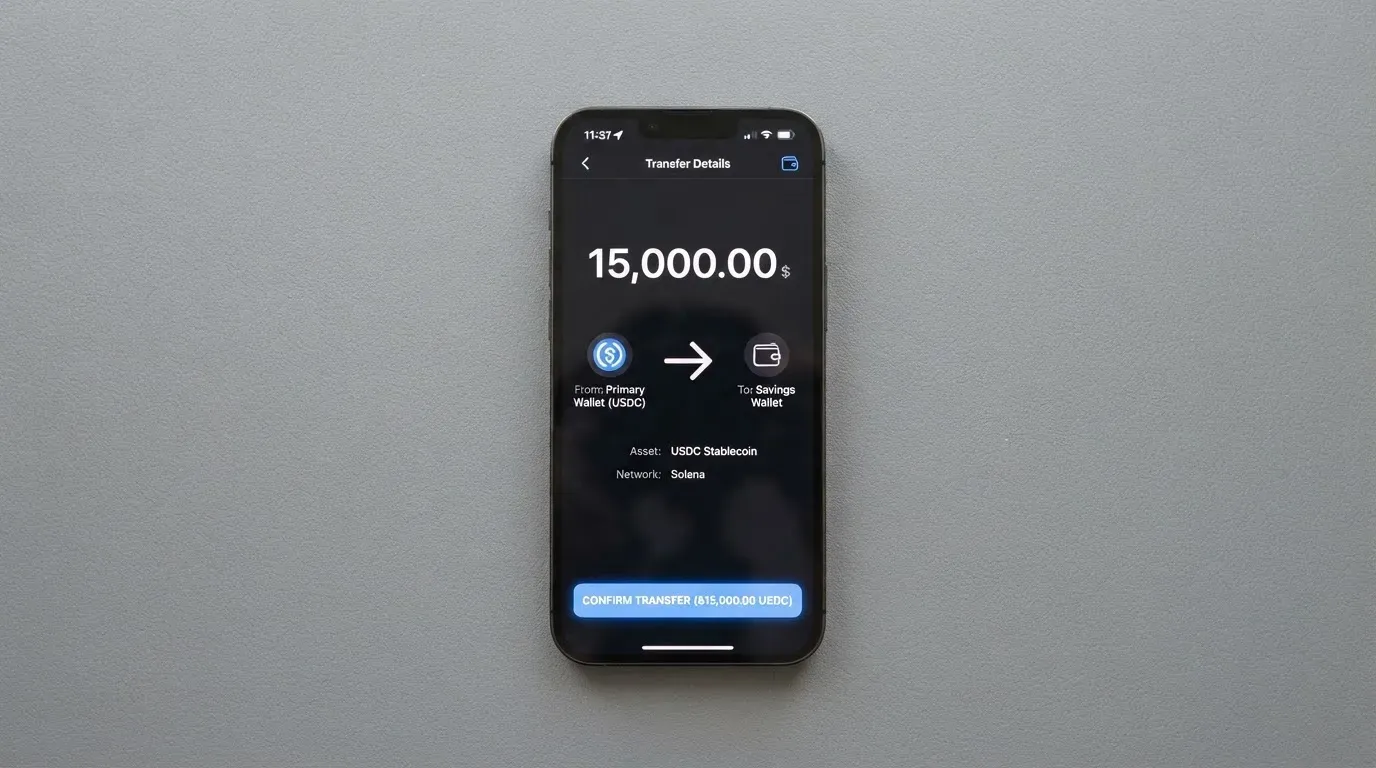
Polygon for both stablecoins is a real convenience. It means two cheap networks cover the bulk of what people actually hold, and network fees on those transfers are typically modest — though the amount is set by the blockchain and not by anyone here.
Two things you should know before your first transfer. Blockchain transfers are irreversible, so a deposit sent on a network the card provider does not support, or sent to an address belonging to a different network, can be lost or need manual recovery with no guarantee. If you are sending USDT, note that USDT exists on several networks — Ethereum, Tron, Solana, Polygon, Avalanche and others — and the one that works here is Polygon. Getting that wrong is the single most common irreversible mistake in this whole category, and it is the one this card’s pages do not warn you about.
Second: top-up and reload are not mentioned. There is one purchase flow described — choose an amount, pay in crypto — and nothing about adding to the card afterwards. For a prepaid product that is an odd silence, and if your plan is “load a little, spend a little, top up again”, that is a question to ask first, because if repeat loading is not supported, the $499 ceiling is a spending budget rather than a top-up.
One more asymmetry: USDT is on Polygon here, while USDC has been supported on a wide set of networks including Ethereum, Solana, Base, Polygon PoS, Avalanche, Arbitrum and Stellar, and it stopped being supported on Tron in February 2024. So the wider USDC ecosystem does not apply to this card — the network that works is Polygon.
Withdrawal is not stated either. The terms say that on termination the right to use the service ceases, and do not address your balance. So I would not treat leftover funds as recoverable, and I would not treat this card as somewhere to park money.
Paying with it day to day
The card supports Apple Pay and Google Pay. That is the single most useful line on the page for everyday use, because a virtual card number that cannot be pushed to a phone wallet is awkward to pay with anywhere that prefers a wallet. Blocked merchant categories are not stated.
Apple Pay works by replacing your card number with a device-specific Device Account Number held in the phone’s Secure Element, not on Apple’s servers, and each payment carries a one-time dynamic security code. The issuer can still restrict a tokenised number — for example block it on magnetic-stripe, phone or website use. So Apple Pay support on the card’s side does not guarantee every payment in every wallet will go through.
Now the 3D Secure point, because I think it deserves more space than a table cell. Three-D Secure is the identity check on online card payments: the issuer assesses the risk and either approves it without friction or challenges you, for example with a one-time code or biometrics. Visa’s brand is Visa Secure, Mastercard’s is Identity Check. This card’s cards do not support it.
What that costs you in practice, at the merchant end: some shops apply extra scrutiny when the issuer country differs from the billing address, and merchants can decline prepaid or foreign-issued cards because the BIN lookup reveals the card type and issuer country. With no 3D Secure on a virtual card from an unnamed issuer country, online acceptance is the part of your life to watch. Declines happen; they are often not personal, but they are yours to retry.
One related mechanism worth knowing, because it catches people abroad: Address Verification Service compares the numeric parts of the billing address you type with the issuer’s records. It is mostly offered in the US, Canada and the UK, and is generally unavailable for foreign-issued cards — which can itself cause declines.
A smaller practical note: a declined authorisation can leave a hold on your funds that stays for several days, typically up to seven. If you are spending from a fixed balance, a stuck hold is a real constraint, not a rounding error.
There is no app mentioned anywhere — purchase is on the web — and no rewards, cashback or incentives are described. Support is a contact page and a Telegram news channel; hours and languages are not stated. If you do need a human, that is what you have, and the response times are anyone’s guess.
What can go wrong
The biggest risk here is not fraud. It is that you are trusting a company whose legal identity the public pages do not give you. The terms describe Card2Crypto as providing software services only. The issuer is not named. The country of registration is not named. No licences are named. Payments are handled by unnamed licensed third-party providers.
That structure is not unusual in this category — plenty of legitimate crypto card brands are fronts for licensed issuers — but legitimate ones usually publish the licence and the issuer. Here you are asked to load money and trust, with the counterparty unnamed. The terms also route disputes to the courts of a country the pages never state.
Let me be clear about what that means for a refund: none for restricted-country activation or for VPN use. A general refund policy is not described. So the two most likely reasons a refund would matter to you are the two where the answer is explicitly no.
Next, VPN use. The pages say VPN use is “strictly prohibited by the card provider” and may lead to cancellation without refund. Read that as a rule with teeth: a VPN breaks the location signal the provider is relying on, and they have said in advance what they do about it. If you use one routinely, this is not a card to experiment with.
Custodial status is not stated. That matters. If the provider holds your credentials, you are trusting them completely — and the record of custodial platforms is not encouraging: Mt. Gox, about US$350 million reported stolen between 2011 and 2014; Coincheck, about US$400 million in 2018; Ronin Network, US$625 million in 2022. Crypto transfers are typically irreversible too, and a stolen private key has no recovery mechanism, because the network cannot freeze or return funds.
On complaints: no official incidents found, and no Trustpilot or Reddit page for Card2Crypto surfaced when I looked — the results were other brands. That silence cuts both ways. It may mean a clean record; it may mean a small or young operation. There is no way to tell the difference from outside, and absence of reviews is not reassurance.
Tether, for its part, says it disables tokens in wallets on the OFAC sanctions list and has frozen funds tied to illicit activity — so even a “private” crypto payment path is not censorship-proof.
The category’s own history is the reason to hold that last point seriously. Visa said in November 2022 that it had “terminated our global agreements with FTX”, and the FTX US debit card programme was wound down by its issuer. Visa also suspended WaveCrest in Europe in 2018, closing every WaveCrest-issued Visa programme. Programme closures typically run like this: a notice period, then loading and spending stop, then users are asked to withdraw remaining balances. One 2026 closure reported by a secondary source had new loads ending 8 July 2026 and spending stopping 8 August 2026 — a single unconfirmed source, so treat it as a shape rather than a fact.
On chargebacks, know what you have and what you don’t. A chargeback is a refund ordered by the issuer to settle a dispute. In the US, debit card reversal rights come from Regulation E and credit card rights from Regulation Z, and prepaid-card coverage varies and should not be assumed. With no 3D Secure, liability for a fraudulent online payment does not shift the way it can under authenticated flows. The practical translation: disputes here are harder, not easier.
And one small thing at the end: a copyright line reads 2022-2026. It is not a track record of audited operation, but it does tell you the site is not older than four years, which for this category is young.
What you could take instead
If the reason you are here is “no KYC”, the alternatives below do not solve that for you — Cardex, CardFlow and HyperCard are all more conventional. They are here for a different reader: one who wants a crypto-funded card from a company that publishes more about itself. Compare them on that basis.
| Card2Crypto | Cardex | CardFlow | HyperCard | |
|---|---|---|---|---|
| Score | 6.0 / 10 | 5.6 / 10 | 4.9 / 10 | 4.7 / 10 |
| Card type | Prepaid virtual debit Mastercard, USD | Debit card on VERVE, VISA, Mastercard and UnionPay; virtual and physical | Virtual USD Mastercard, created in about 3 minutes | Prepaid “HyperCard”; network not stated; USD or EUR balance |
| Who it is for | “Anyone worldwide can purchase”, minus a 30-country refusal list | “One crypto card, 200+ countries”; no exclusions listed | Aimed at Nigeria; “Nigerians and global users” | No country list; “more than 176 countries” of acceptance |
| Cost | Not stated; 5–499 USD | Not stated | “Creating a virtual card is completely free” | Not stated |
| Funding | USDT and USDC (Polygon), BTC, ETH, SOL, XMR | USDT, USDC and BTC wallets; networks not stated | Bitcoin, USDT, ETH or Naira bank transfer | USDT, BTC, ETH in the app; converted to USD or EUR |
| Conversion fee | Not stated for the Mastercard | Not stated; site describes an “AI-Powered Conversion Rate” | Not stated | Not stated |
| Notable gap | Issuer, country, licences unnamed | Card currency Naira per the App Store listing | Target market is clearly Nigeria | Network not stated on the App Store page |
What Cardex does differently. It runs on four networks, including Mastercard and UnionPay, and offers physical as well as virtual cards — a genuinely different proposition for anyone who needs plastic or a local rail. Its App Store listing is Naira-focused, paying in Naira, which tells you more about its centre of gravity than the “200+ countries” line does. Its conversion page describes scanning global exchange rates at the moment of payment to pick the best one, with no fee percentage published.
What CardFlow does differently. It is the cheapest entry of the group on the face of it — creating a virtual card is free — and it takes Naira bank transfer alongside Bitcoin, USDT and ETH. But it describes itself as “Nigeria’s smartest fintech card platform” aimed at Nigerians and global users, so it is a Nigeria product that also serves others, and you should read it that way.
What HyperCard does differently. Two things: it holds USD or EUR rather than dollars only, and it works in “more than 176 countries”. Read the second one carefully — that is a statement about acceptance, not eligibility. Its App Store page lists no fees and does not name the network.
Honest comparison: none of the three names an issuer or a licence either, and none publishes a conversion fee percentage. All three publish less about the thing you would want to know than you would like. Cardex and CardFlow at least tell you which networks they run on and what they cost to open. On everyday use, none of them solves the no-3D-Secure issue either.
Who I would recommend it to
I would recommend this card to one specific person. You hold crypto on-chain already, you have no working route to an ordinary bank card, and you need a USD card number today for a specific payment you can name. You are comfortable topping up in small amounts, you treat the balance as spending money rather than savings, you will not use a VPN, and you accept that if something goes wrong you will be dealing with a support contact page and a Telegram channel with no published hours.
I would not recommend it if any of these are true. You want a card for travel — one currency, no ATM position, and online acceptance without 3D Secure is not built for it. You want to dispute a charge. You want to know who your issuer is and what protects your money, because the pages do not tell you and the terms describe the company as software services only. You want to hold a balance. You want to be able to close an account and get money back.
For everyone else, the honest summary is this: Card2Crypto offers a genuinely unusual thing — a prepaid Mastercard with no identity check — and asks in exchange for your trust in a company that publishes very few verifiable details about itself. If the no-KYC part is the requirement, this is a real answer to it. If the question is “is this safe”, the pages do not contain enough to answer that, and I would rather say so than dress the silence up as reassurance.
Frequently asked questions
What is Card2Crypto card?
It is a prepaid virtual debit Mastercard with a USD balance, sold on the web and paid for in crypto. You choose an amount between 5 USD and 499 USD, pay, and receive a card number. It is virtual only — no plastic — and it supports Apple Pay and Google Pay. Cards do not support 3D Secure, which affects how many online shops will accept them.
Does Card2Crypto require KYC?
No. The card’s pages state that all cards can be purchased and activated without KYC, and there are no KYC tiers at any level. Activation may still ask for a valid name, email, phone number and billing address. That is contact and address detail, not identity verification, but if you have never given that detail anywhere, this is where you will first be asked.
Is Card2Crypto a bank?
On the evidence of its own pages, no — or at least it does not present itself as one. The terms describe Card2Crypto as providing software services only. The issuer, the country of registration and any licences are not named, and payments are said to be handled by unnamed licensed third-party providers. So the banking and card-issuing work sits with parties the pages do not identify.
Who can get the card?
The card says anyone worldwide can purchase it. But activation may be refused to residents of 30 listed countries, including Russia, Belarus, Serbia, Turkey and Ukraine, and the refusal is based on residence rather than citizenship. Attempting to activate from a restricted country voids any right to refund, which means the check happens after you have paid.
How much does a Card2Crypto card cost?
The page says “no fee stated”, which is not the same as free. The card value you choose runs from 5 USD to 499 USD, and no monthly fee is stated. The 4–7% figure you may see on the same page belongs to the PayPal gift card, not to the Mastercard. What you pay loading the card, plus the blockchain’s own network fee on your transfer, is the cost you can actually count.
How do I top up the Card2Crypto card?
You pay in crypto at purchase: USDT or USDC on Polygon, or Bitcoin, Ethereum, Solana or Monero. What the pages do not describe is topping up again — reload is not mentioned — so confirm that before planning on adding funds later. Transfers are irreversible, so send USDT on Polygon, not on another network, or the deposit can be lost with no guarantee of recovery.
Is the Card2Crypto card safe?
I cannot tell you that, and neither can the pages. Custodial status is not stated, so it is unclear who holds your credentials. There is no 3D Secure, there is no general refund policy described, and disputes go to the courts of an unnamed country. No complaints surfaced when I looked, which is not the same as a clean record. Treat it as a small convenience, not as somewhere to hold money.
Can I use the Card2Crypto card in my country?
Two different questions hide in that. Whether you can *activate* it depends on the 30-country residence list. Whether you can *spend* it depends on the shop: merchants can decline prepaid or foreign-issued cards after looking up the BIN, and address verification is generally unavailable for foreign-issued cards. The card also holds a USD balance only, so a non-dollar purchase involves a conversion whose fee is not stated.
Does Card2Crypto have a mobile app?
No app is mentioned anywhere — purchase happens on the web. For everyday payment, Apple Pay and Google Pay are the supported route, which means adding the virtual card to your phone wallet rather than opening an app. Support runs through a contact page and a Telegram news channel, with no hours or languages published.
Is Card2Crypto worth it?
For a one-off payment you can name, when you have crypto on-chain and no bank card, yes — that is a real gap it fills. For anything ongoing, no: no plastic, no rewards, no published fees, no reloads, no issuer named. Compare Cardex, CardFlow or HyperCard if a more conventional card from a company that says more about itself fits what you actually need.
Choosing a virtual card – cryptocardadvisor
Content created by the «cryptocardadvisor» team